5 Costly Mistakes Miami First-Time Homebuyers Make — and How to Avoid Them
Buying a home in Miami can be expensive. But for first-time buyers, costly mistakes — from underestimating closing costs to taking on new debt — can add thousands of dollars to the price of homeownership or derail a purchase altogether.
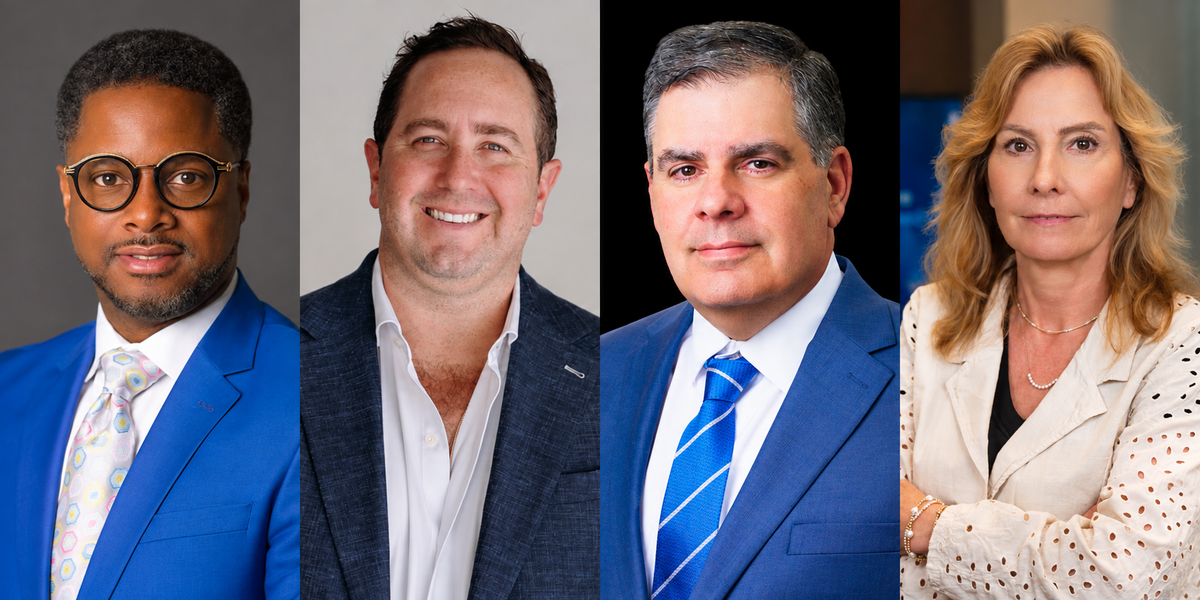
One buyer lost their deposit after financing a car before closing on a home, while another discovered about $100,000 in property damage after hiring an inadequate inspector. Mortgage lending professionals, a real estate advisor and an attorney say these costly mistakes highlight the importance of financial planning and due diligence before purchasing a home.
1. Buying More Than You Can Afford
Qualifying for a mortgage doesn't necessarily mean a buyer can comfortably afford the monthly payments.
Danny Felton, branch manager at Primary Residential Mortgage in Miami Gardens, said buyers often overlook everyday expenses when determining how much they can afford.
“Don't buy what you qualify for. Buy what you can afford,” Felton said.
He recommends factoring in expenses such as child care, health insurance and transportation before setting a homebuying budget.
2. Underestimating Closing Costs
Saving enough for a down payment is only part of the financial preparation required to buy a home.
Heidi Ciuffetelli, head of consumer lending at ConnectOne Bank, said first-time buyers shouldn’t overlook closing expenses such as appraisal fees, title insurance and loan application costs.
Buyers should ensure they have enough funds to cover both the down payment as well as closing costs. A dedicated lending partner can help first-time buyers understand what they can afford and any programs that might be available.
ConnectOne Bank’s First-Time Homebuyer Program offers up to $1,000 in closing costs credit, an application fee credit and an interest rate discount. The bank also pays private mortgage insurance for qualifying borrowers, Ciuffetelli wrote in an email to Miami Affordable Magazine.
Eligibility depends on the county where the property is located and the borrower’s income, she said.
Morritt Hock & Hamroff attorney Gary Rosner said buyers generally receive a loan estimate outlining closing costs and a closing disclosure three business days before closing.
These documents allow buyers to review their expenses and identify unexpected charges before finalizing a purchase.
Felton also emphasized the importance of budgeting for prepaid homeowners insurance and property taxes.
Florida homeowners face some of the highest insurance costs in the country. In 2026, the average annual homeowners insurance rate in Florida was $8,471, compared with $1,844 in New York and $1,653 in California, according to Insurance.com. The estimates are based on policies with $300,000 in dwelling coverage.
Florida's exposure to hurricanes and other severe weather increases the risk of property damage, contributing to higher insurance costs.
3. Taking on Additional Debt Before Closing
Buying a car or opening another line of credit before closing on a home can jeopardize mortgage approval.
Felton recalled a client who was approved for a mortgage but financed a car before closing. The new loan appeared on the buyer's credit report before the buyer even picked up the vehicle.
The additional debt pushed the buyer's debt-to-income ratio beyond the lender’s guidelines, preventing the home purchase from going through.
The buyers also lost their deposit. Felton confirmed that their financing contingency had expired, meaning that the contractual deadline for obtaining financing protection had passed. He explained that buyers who fail to secure financing within their contracts deadlines risk losing their deposits.
Rosner also warned that financing contingencies and contract deadlines can affect buyers' legal protections.
“One of the best ways to protect your deposit is to have an attorney review the contract with you before you sign it,” Rosner said.
4. Overlooking Hidden Homeownership Expenses
A mortgage payment is only one of the expenses that come with owning a home.
Christopher Wands, executive director of luxury sales at Douglas Elliman Real Estate, said buyers sometimes underestimate property taxes, insurance, homeowners association fees and utilities.
One common mistake is relying on property tax estimates listed on real estate websites.
Wands said those figures may reflect what a previous owner paid rather than what a new buyer will owe after the property is reassessed.
Felton offered an example: A seller benefiting from a homestead exemption might pay $3,000 annually in property taxes, while a new buyer could face an $8,000 bill after reassessment.
According to the Miami-Dade County Property Appraiser, a property's assessed value may reset to market value after a sale. The previous owner's homestead exemption and Save Our Homes assessment limitation generally do not transfer to the new owner.
Florida's homestead exemption can reduce the taxable value of an eligible primary residence. Homeowners must apply and meet residency requirements, according to the Property Appraiser's Office.
The state's Save Our Homes provision also limits annual increases in assessed value to 3% or the rate of inflation, whichever is lower.
Condominium purchases carry additional financial risks.
Ciuffetelli warned that structural problems can significantly increase homeowners association fees.
Rosner advised condo buyers to investigate upcoming special assessments and required building inspections. Depending on the building and the extent of major repairs, special assessments could reach $40,000 to $50,000, hypothetically he said.
Felton recommended obtaining a condominium questionnaire and reviewing the association's budget before purchasing.
These documents can help buyers determine whether a building has adequate financial reserves, outstanding obligations or upcoming special assessments.
He also recommended checking how many condominium units are owner-occupied compared with investor-owned.
Wands similarly advised reviewing association budgets, reserve studies, upcoming special assessments and building insurance coverage.
Beyond condominium finances, buyers should also pay close attention to a property's physical condition.
Wands described a client who hired an inadequate inspector and later discovered approximately $100,000 in property damage.
He recommends hiring experienced professionals and understanding a property's condition before completing a purchase.
5. Ignoring Credit Before Buying
A buyer's credit history can affect both mortgage eligibility and borrowing costs.
Ciuffetelli said credit scores play a significant role in determining whether buyers qualify for a mortgage and the interest rates they receive.
Felton encourages prospective buyers to monitor their credit and establish a budget before beginning the home-buying process.
Felton also hosts free, in-person, HUD-approved eight-hour homebuyer education workshops covering budgeting, credit and the home-buying process.
English-language workshops are scheduled for the second Saturday of each month from 8:30 a.m. to 4 p.m. at the Oasis at Miami Gardens Event Center, 640 NW 183rd St., Miami Gardens.
Haitian Creole workshops take place on the fourth Saturday of each month from 11 a.m. to 5p.m. at the North Miami Public Library, 835 NE 132nd St., North Miami.
The workshops are open to Florida residents. Participants can register at https://www.ercchelp.org/events or call 305-652-7616.
“Invest your time before you invest your money,” Felton said.


Comments ()